
AI’s capital call

 S&P 500 -1.21% to 7,663.43 US 10-year yield -17.2 basis points to 4.957% Spot gold -2.80% to $4,024.35 an ounce DXY -0.07% to 101.62
What to look out for today
Companies reporting on Friday, 23nd October: American Express, SLB
Key data to move markets today
EU: Eurozone, German and French HCOB Composite, Manufacturing and Services PMIs and a speech by ECB Executive Board member Piero Cipollone
UK: Retail Sales, Retail Sales ex-Fuel, S&P Global Composite, Manufacturing and Services PMIs
US: S&P Global Composite, Manufacturing and Services PMIs, Michigan Consumer Expectations and Sentiment Indices, and UoM 1- and 5-year Consumer Inflation Expectations
Global Macro Updates
Can Meta afford to be right? Meta’s financing question is becoming harder to separate from its investment case. Bloomberg reported $825 billion of future lease and contractual commitments alongside negative Q3 FCF of $2.12 billion. The five-year CDS reached roughly 119 basis points. The Nasdaq Composite’s decline captures the broader repricing, as investors question not only who supplies AI infrastructure, but who finances its eventual returns and how long it will take.
The non-voting share class would let Meta raise equity without surrendering Zuckerberg’s control. That creates financing flexibility, as additional borrowing increases fixed claims on future cash flows, while equity issuance dilutes existing shareholders.
Agentic shopping could nevertheless transform Meta’s economics. Controlling product discovery, comparison and purchasing would move the company closer to transactions, rather than simply monetising attention. For Meta to succeed, transaction volumes must translate into retained revenue after inference, customer acquisition and infrastructure costs.
For Meta, the decisive evidence will be improving agent economics and cash generation relative to the capital committed, not adoption alone.
US Stock Indices
Dow Jones Industrial Average +0.02%
Nasdaq 100 -2.90%
S&P 500 -1.21%, with 5 of the 11 sectors of the S&P 500 down
The enormous cost of building AI infrastructure is pushing tech giants to seek ever more funding, prompting warnings from Wall Street.
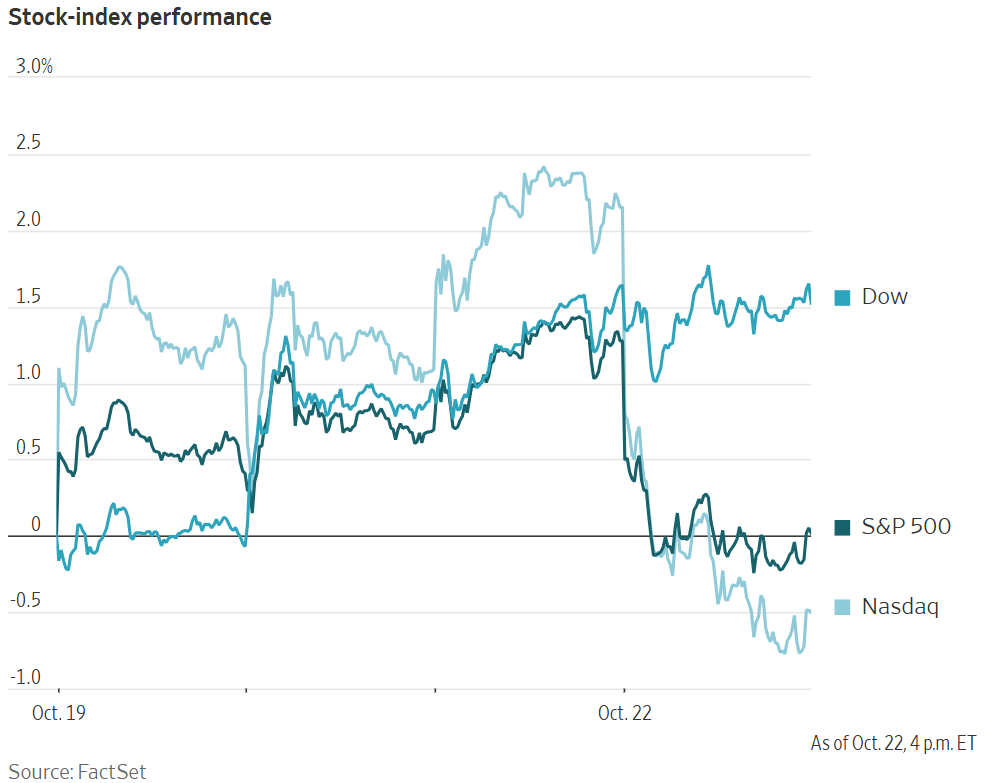
Signs that Meta Platforms may launch a major fundraising effort helped drive another sharp market rotation on Thursday, as investors sold AI-linked stocks and shifted into most other sectors. The S&P 500 Communication Services sector fell -3.01%, followed by Information Technology at -3.00%. Consumer Staples gained +3.11%, while Utilities rose +1.98%.
US equity indices were mixed on Wednesday, with the Dow Jones rising on the day, as the S&P 500 and Nasdaq Composite both declined. The Dow Jones Industrial Average advanced 11.89 points, or +0.02%, to 52,867.98, the S&P 500 traded 93.74 points lower, or -1.21%, to 7,663.43 and the Nasdaq Composite fell by 694.00 points, or -2.60%, to 26,008.86.
In corporate news, PepsiCo said Thursday that it had renewed its longstanding partnership with Taco Bell through 2036, a week after sister chain KFC announced plans to switch to Coca-Cola as its US beverage supplier. The agreement also covers Pepsi products in Taco Bell’s international markets, including Canada, the United Kingdom, Ireland and Thailand.
Moderna shares fell Thursday after closely guarded results from an mRNA-based cancer vaccine study leaked on social media. OncologyCentral appeared to publish some findings that day, according to screenshots on X cited by The Wall Street Journal. The results were due for release Saturday at the European Society for Medical Oncology conference.
The vaccine reduced the risk of cancer spreading by 38% in patients with high-risk melanoma compared with standard immunotherapy, a favouable result that nonetheless missed elevated market expectations. Weaker results in the late-stage trial than in the mid-stage study may also suggest a lower chance of success against cancers that have spread throughout the body or more difficult tumors. Moderna and Merck are testing the vaccine in several cancer types.
Corporate Earnings Reports
Posted on Thursday, 22 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
American Airlines reported third-quarter revenue of $16.34bn, up +19.3% y/y, beating estimates of $16.21bn, and an adjusted EPS loss of -$0.28 vs -$0.36 expected. Surging fuel expenses rose +67.5% y/y to $4.64bn, pressuring profitability. For the full year 2026, management widened its expected adjusted EPS loss to between -$1.60 and -$1.00 vs -$0.94 expected. For the fourth quarter, adjusted EPS is projected between -$1.10 and -$0.50 vs -$0.47 expected, with total revenue up +19.5% to +22.5% y/y. The chief executive stated that the airline delivered record third-quarter revenue and the strongest year-over-year revenue growth of his career, led by premium performance.
Blackstone reported its Q3 2026 financial results. Adjusted EPS reached $1.32 vs $1.28 expected, down -13% y/y, while adjusted revenue was $3.22bn vs $3.28bn expected, fell -3% y/y. Total assets under management rose +10% y/y to $1.37trn, supported by quarterly inflows of $63.3bn vs $58.83bn expected. Fee-related earnings increased +6% y/y to $1.57bn vs $1.59bn expected, whilst total distributable earnings dropped -9% y/y to $1.72bn. The firm announced a quarterly dividend of $1.12 per share, distributing $1.5bn to shareholders through dividends and share repurchases. Management stated that Blackstone delivered strong third-quarter results amid a volatile external environment.
Comcast reported Q3 2026 revenue of $29.30bn vs $29.25bn expected, down -6.1% y/y, and adjusted EPS of $1.07 vs $0.98 expected, down -4.0% y/y. Adjusted EBITDA reached $9.11bn vs $8.9bn expected, whilst free cash flow rose to $4.21bn vs $3.2bn expected. Segment revenue for Media grew +13.0% y/y to $5.36bn and Business Services increased +2.7% y/y to $2.65bn, offset by Residential Connectivity and Platforms falling -3.5% y/y to $17.02bn and Theme Parks declining -4.4% y/y to $2.60bn. Domestic wireless lines added 368,000 net subscribers, while broadband recorded net losses of 144,000. Management stated that Peacock delivered its second consecutive profitable quarter, generating $261mn in adjusted EBITDA driven by strong distribution growth.
Honeywell International reported its Q3 2026 results, posting revenue of $4.99bn, up +1.3% y/y vs $5bn expected, and adjusted EPS of $2.27, up +34% y/y vs $2.17 expected. Segment revenue included Building Automation at $2.02bn, up +7.6% y/y, Process Automation and Technologies at $1.86bn, and Industrial Automation at $1.12bn. Free cash flow rose +15% y/y to $688mn. Honeywell raised its full-year 2026 guidance, lifting adjusted EPS expectations to between $8.40 and $8.45 vs $8.30 expected, organic sales growth to between +4% and +5%, and free cash flow to approximately $2.1bn, while adjusting revenue guidance to between $20.00bn and $20.10bn vs $20.13bn expected. The chief executive stated that the raised full-year outlook reflected strong operational execution and reinforced confidence in delivering on long-term 2029 targets.
Lockheed Martin reported third-quarter revenue of $20.71bn vs $20.49bn expected, up +11% y/y, and earnings per share of $7.97 vs $7.43 expected. Operating profit reached $2.44bn, while backlog reached a record $292.0bn. For full-year 2026, the company guided net sales to between $80.00bn and $82.00bn alongside EPS of $30.35 to $30.75. Concurrently, the Pentagon finalised a 10-year agreement securing a minimum of 850 F-35 jets, with Lockheed Martin self-funding at least $7bn in programme initiatives. Leadership stated that sustained financial momentum across the portfolio provided confidence to increase full-year outlook for sales, earnings, and cash flow.
Procter & Gamble reported its Q1 2027 financial results before market open, beating consensus estimates. Net sales rose +4% y/y to $23.28bn vs $22.79bn expected, while core EPS grew +1% y/y to $2.00 vs $1.88 expected. Organic sales rose +4% y/y, led by Beauty up +5.4% y/y, Fabric & Home Care up +4.8% y/y, and Grooming up +4.5% y/y. For fiscal 2027, the company forecasts net sales growth of up +2% to +4% and adjusted EPS of $6.89 to $7.11 vs $6.97 expected, incorporating the Thorne acquisition while absorbing a $1.4bn after-tax commodity cost headwind. Management stated that despite ongoing geopolitical and economic challenges, the strong start keeps the group on track to deliver within full-year guidance ranges.
Spotify reported its third-quarter results before market open, posting revenue of €4.97bn vs €4.98bn expected, up +16% y/y, and diluted EPS of €2.48 vs €2.81 expected, down -24% y/y. Operating income rose +15% y/y to €672mn, and gross margin reached 33.0%. Total premium subscribers climbed +9% y/y to 306mn, crossing the 300mn milestone, whilst monthly active users grew +11% y/y to 788mn. For the fourth quarter, Spotify forecast revenue of €5.2bn vs €5.23bn expected and operating profit above estimates at €820mn vs €813mn expected, supported by returns on artificial intelligence initiatives. Year-to-date share repurchases totalled $1.1bn through 21 October 2026.
Union Pacific reported Q3 2026 operating revenue of $7.20bn, up +15% y/y, beating consensus estimates of $7.11bn. Adjusted EPS reached $3.53, up +15% y/y vs expectations of $3.47, excluding $22mn in acquisition-related expenses, while GAAP EPS was $3.49. Total freight revenue rose to $6.81bn, supported by revenue carload volumes rising +6% y/y and core pricing gains. Across freight segments, premium revenue increased +21% y/y, industrial rose +14% y/y, and bulk grew +10% y/y. The operating ratio was 59.1%. For full-year 2026, the company reaffirmed its targets, projecting high-single-digit reported EPS growth and a $3.5bn capital programme. Management stated that results demonstrated their operational efficiency amidst volume growth as they advance through the Surface Transportation Board merger review process.
Valero Energy reported Q3 2026 revenue of $46.10bn and adjusted EPS of $23.90 vs $20.97 expected, up +553% y/y. Operating income reached $8.8bn in refining, $353mn in renewable diesel, and $272mn in ethanol, which rose +49% y/y. Total throughput averaged 3.0mn barrels per day, supported by the completed St. Charles FCC unit optimisation project. For Q4, the company expects refinery utilisation between 80% and 83%, alongside renewable diesel sales volumes of 325mn gallons and sustained higher flows through the Strait of Hormuz. Management stated that refineries operated at near-record utilisation rates to provide reliable fuel supplies.
Hasbro reported Q3 2026 revenue of $1.60bn vs $1.48bn expected, up +15% y/y, alongside adjusted EPS of $2.90 vs $1.86 expected. Adjusted operating profit rose +52% y/y to $541mn, while adjusted EBITDA reached $604.5mn vs $442mn expected. Operational growth was led by the Wizards and Digital Gaming segment, where revenue climbed +31% y/y to $747.2mn on Magic: The Gathering sales that increased +34% y/y to $616.1mn, whilst Consumer Products revenue rose +4% y/y to $827.9mn. For the full year 2026, the company raised its guidance, projecting adjusted EBITDA of $1.58bn to $1.63bn vs $1.47bn expected and constant-currency revenue up +7% to +9%. Management stated that momentum across the Magic portfolio is expected to deliver a strong finish to 2026 and sustain growth into 2027.
Bloom Energy reported third-quarter revenue of $1.24bn, up +138.1% y/y, vs consensus estimates of $1.07bn, alongside adjusted EPS of $0.94 vs $0.68 expected. The company achieved an adjusted gross margin of 34.5% and announced its addition to the S&P 500 index. Following the performance, Bloom Energy raised its full-year 2026 revenue guidance to between $4.4bn and $4.6bn, up from its prior range of $3.9bn to $4.2bn, whilst increasing its full-year adjusted EPS outlook to between $3.10 and $3.40 vs $2.73 expected.
Deckers Outdoor reported Q2 FY27 revenue of $1.48bn vs $1.51bn expected, up +3.5% y/y, and diluted EPS of $2.31 vs $1.79 expected, which included a $46.0mn tariff refund benefit. Brand sales were driven by HOKA, which rose +6.8% y/y to $677.2mn, whilst UGG grew +3.5% y/y to $786.4mn. For full-year FY27, Deckers lowered its revenue guidance to between $5.70bn and $5.73bn vs $5.88bn expected, but raised its EPS outlook to between $7.80 and $7.95 vs $7.53 expected. Management stated that the company is taking deliberate actions to strengthen consumer connection, sharpen operational execution, and concentrate resources on its greatest opportunities.
MaxLinear reported its Q3 2026 results after market close, delivering revenue of $218.1mn vs $211mn expected, up +72% y/y, and adjusted EPS of $0.62 vs $0.55 expected, up +343% y/y. Gross margin reached 60.0%, while infrastructure growth was up +210% y/y and GAAP net income stood at $28.9mn. For Q4 2026, the company guided revenue of $240mn to $260mn vs $221mn expected, with non-GAAP gross margin between 59.0% and 62.0%, while raising its full-year 2026 optical data centre outlook to $250mn to $270mn. Additionally, MaxLinear increased its credit facility by $70mn to $200mn. Management stated that strong momentum in its optical AI data centre business reflected the volume ramp of its Keystone PAM4 DSP platform and the strength of its expanding infrastructure portfolio.
Newmont reported third-quarter 2026 revenue of $6.36bn, up +15% y/y vs $6.31bn expected, and adjusted EPS of $2.20 vs $2.11 expected. Adjusted EBITDA reached $3.95bn vs $3.78bn expected, whilst free cash flow stood at $1.91bn vs $3.36bn expected. Attributable gold production was 1.30mn ounces with an all-in sustaining cost of $1,454/oz. For the full year 2026, the group guided attributable gold production of 5.3mn ounces with an AISC of $1,520/oz, sustaining capital of $1.95bn, and development capital of $1.4bn. The board declared a dividend of $0.26 per share. Management stated that Newmont remains on track to meet full-year 2026 production guidance and improved cost targets, supported by disciplined operational execution.
Western Digital reported Q1 FY27 net revenue of $4.38bn, up +55% y/y vs $4.13bn expected, and adjusted EPS of $4.64, up +161% y/y vs $4.07 expected. Adjusted gross margin reached 58.1%, while operating cash flow stood at $1.60bn. For Q2 FY27, the company guided revenue of $5.00bn to $5.20bn vs $4.57bn consensus, adjusted EPS of $5.60 to $6.00 vs $4.78 consensus, and adjusted gross margins of 60% to 61%. Western Digital repurchased $1.00bn of stock and increased its quarterly dividend by +17% to $0.175 per share. Management noted that fiscal 2027 was off to a strong start with results beating expectations driven by robust customer demand and disciplined execution.
European Stock Indices
CAC 40 -1.39%
DAX -1.07%
FTSE 100 -0.26%
Commodities
Gold spot -2.80% to $4,024.35 an ounce
Silver spot -5.81% to $54.59 an ounce
West Texas Intermediate +1.42% to $99.10 a barrel
Brent crude +3.16% to $113.13 a barrel
Gold fell to its lowest level since 3 August on Thursday as the spike in oil prices raised concerns that the Fed may keep interest rates elevated for longer and investors positioned themselves for next week’s Fed meeting.
Spot gold declined -2.80% to $4,024.35 per ounce.
India, the world's largest silver consumer, issued permits to import around 6,500 metric tons over the next six months to meet festive-season demand.
Spot silver fell -5.81% to $54.59 per ounce.
Oil prices reached a five-month high on Thursday as Houthi attacks in Saudi Arabia heightened concerns over further disruptions to energy supplies from the key exporting region.Brent recorded its highest close since 4 May and remained in technically overbought territory for the third time in a week.
Brent futures rose $3.47, or +3.16%, to settle at $113.13 per barrel. WTI gained $1.39, or +1.42%, to close at $99.10 per barrel.
After Wednesday's oil market close, the US State Department ordered non-essential staff and family members to leave its embassy in Saudi Arabia. Spokesperson Tommy Pigott attributed the decision to increased hostile activity by Yemen's Houthis against Saudi Arabia.
Saudi Aramco instructed staff to evacuate its headquarters in Dhahran, on the Gulf near Bahrain, Reuters reported, as fighting intensified between the world's largest crude exporter and Yemen's Houthis.
Clashes between the Houthis and the Saudi-led coalition backing Yemen's internationally recognised government have continued since the Iran-aligned group advanced towards Bab el-Mandeb, a shipping chokepoint at the mouth of the Red Sea.
In the US, Valero Energy opened the refiners' earnings season on Thursday with record quarterly profit. It exceeded the market expectations outlined in Precision under Pressure, our latest edition of our Earnings Scoreboard.
Russia struck Kyiv with ballistic missiles overnight, while Ukraine launched hundreds of drones towards Moscow, as hostilities continued despite the latest US effort to end the war.
Russia said on Wednesday that it was ready to resume US-mediated talks with Ukraine next month, following talks between President Vladimir Putin and US envoy Steve Witkoff in St Petersburg.
Ukrainian President Volodymyr Zelenskiy expressed hope that negotiations, the first since February, would begin in early November.
Senior Russian political and energy officials urged the EU on Thursday to reconsider its planned ban on Russian LNG imports, arguing that low gas storage levels had left Europe in a precarious position.
Meanwhile, the European Parliament approved a three-year delay to EU methane emissions rules for oil and gas imports following pressure from governments including France and the US.
In Libya, the closure of a valve on the pipeline linking the Hamada and Tahara oilfields to Zawiya port reduced production at both fields, the head of the National Oil Corporation told Reuters on Thursday.
Note: As of 4 pm EDT 22 October 2026
Currencies
EUR -0.16% to $1.1214
GBP +0.04% to $1.3399
Bitcoin -4.07% to $81,192.42
Ethereum -4.44% to $2,380.79
The yen gained +0.87% to ¥156.76 per dollar on Thursday, recording its strongest daily advance in almost a month.
The euro declined -0.16% against the US dollar, while the dollar index fell -0.07% to 101.62.
Sterling strengthened +0.04% to $1.339.
Fixed Income
US 10-year Treasury -17.2 basis points to 4.957%
German 10-year Bund -7.0 basis points to 3.362%
UK 10-year Gilt -4.2 basis points to 5.338%
US Treasury yields fell sharply on Thursday.
The 10-year Treasury yield declined -17.2 bps to 4.957%, its largest daily fall since 10 March 2023, after reaching 5.365% on 7 October, its highest level since April 2002.
At the long end, the 30-year Treasury yield fell -12.8 bps to 5.284%, its largest daily decline since August 2024. The two-year Treasury yield, which typically tracks expectations for the Fed funds rate, fell -16.2 bps to 4.646%, its largest decline since August 2025.
Analysts described the $26 billion auction of five-year Treasury Inflation-Protected Securities (TIPS) as solid, with non-dealer bidding at 94.5%, above the 90.8% average for the previous six auctions.
On the economic front, the Labor Department reported that weekly initial jobless claims fell by 6,000 to a seasonally adjusted 194,000, below economists' forecast of 200,000. The figures suggested that the laboor market may be regaining momentum after a sluggish September.
The US 2s10s yield curve stood at 31.1 bps, 1.0 bp narrower than Wednesday.
Markets are pricing in a 92.8% probability that the Fed would keep rates unchanged at its 27 – 28 October meeting, from 72.3% a week ago. They also assigned a 80.5% probability that the Fed funds target range would be at least 25 bps higher in December, according to CME Group's FedWatch Tool.
Eurozone government bond markets diverged on Thursday, with French OATs again underperforming as German yields declined.
France's 10-year OAT yield rose +7.5 bps to 5.076%, bringing its increase so far this week to 29.0 bps. The spread over Bunds widened 14.5 bps to 171.4 bps, its widest since November 2011 and 49.0 bps above Italy's BTP spread of 122.4 bps.
Italy's 10-year BTP yield rose +2.0 bps yesterday to 4.586%.
Germany's 10-year Bund yield fell -7.0 bps to 3.362%, while the two-year Schatz yield declined -5.5 bps to 3.064%. At the long end, the 30-year yield decreased -7.7 bps to 3.684%.
Money markets priced the ECB deposit rate at 3.15% by the end of 2027, implying two increases of 25 bps each and an 80% probability of a third.
Note: As of 4 pm EDT 22 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
This article is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced here. Trading financial instruments involves significant risk of loss and may not be suitable for all investors. Past performance is not a reliable indicator of future performance.
 Back to all insights




Created by professionals. For professionals.
